Corporate · 2026-08-26
Class A/A+ office vacancy in Mexico City dropped to 17.2% this quarter and net absorption turned positive again. But 75% of that gross demand didn't come from new companies — it came from renewals, expansions, subleasing and pre-leasing. This is a market reorganizing, not growing.
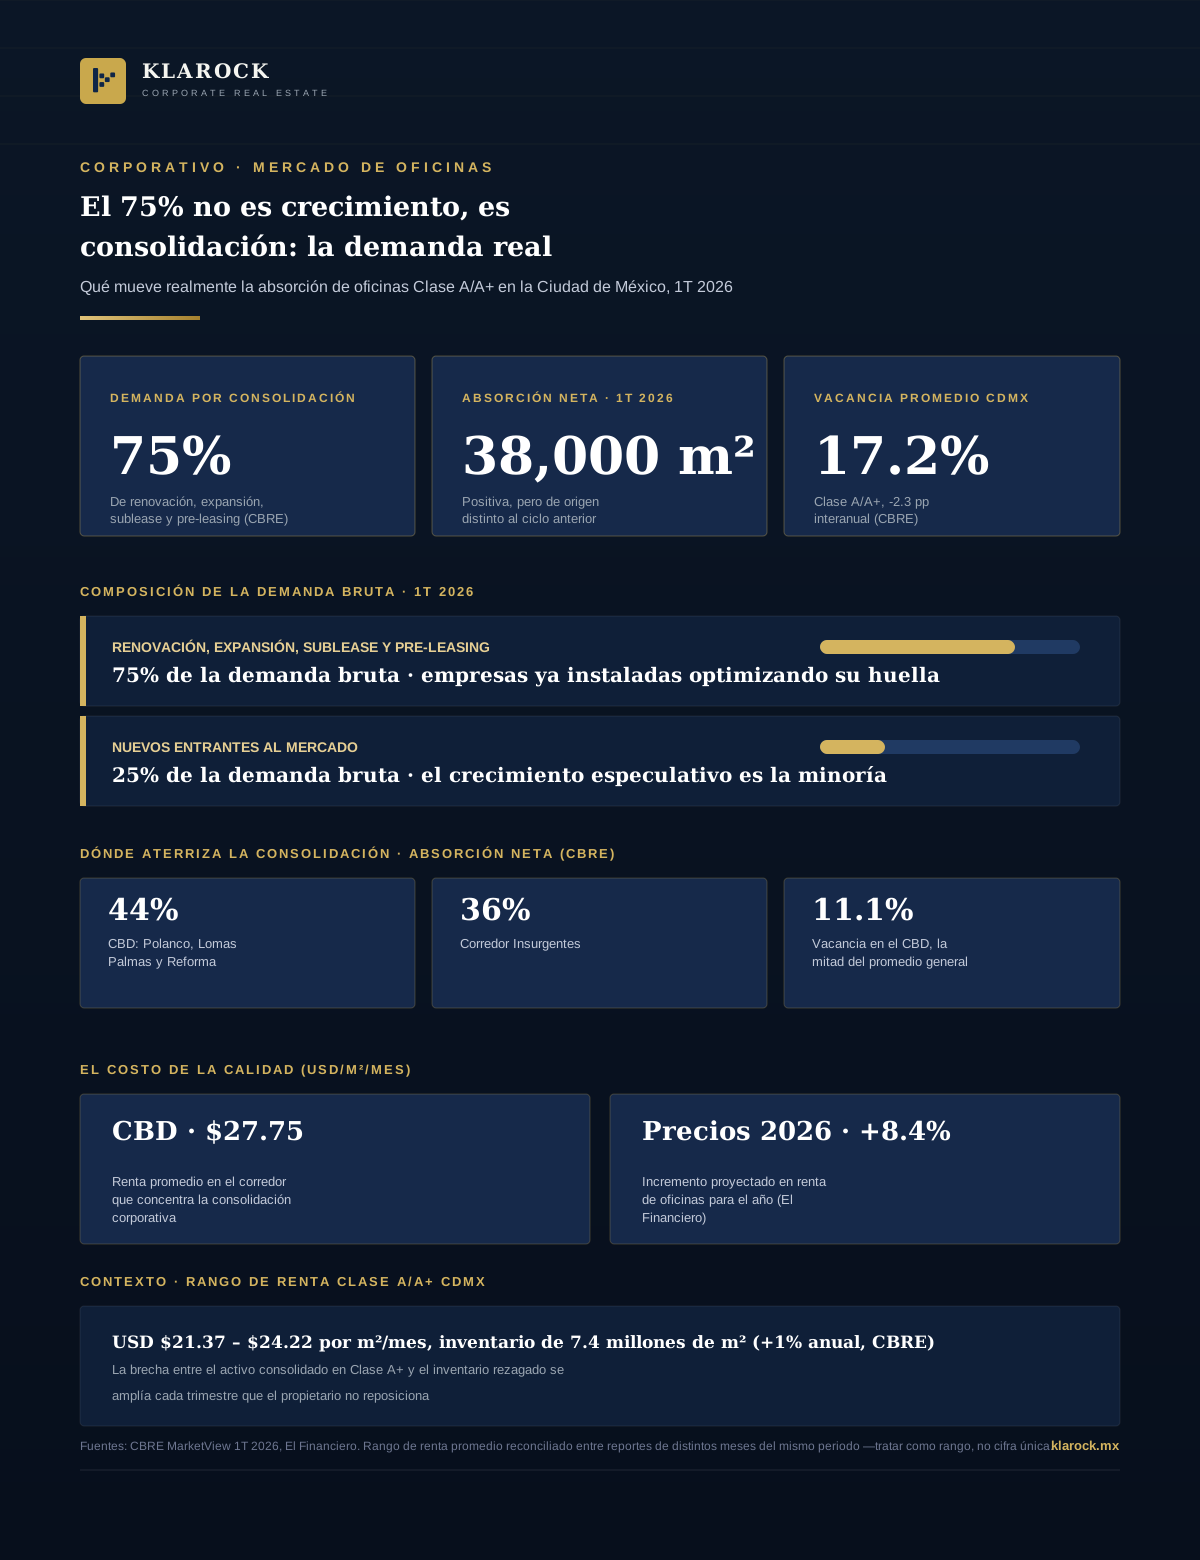
Every quarter office vacancy drops, the narrative simplifies to "the market is recovering." That's true in aggregate: CBRE reported Class A/A+ vacancy of 17.2% in Mexico City during the first quarter of 2026, a 2.3-percentage-point improvement year over year. But underneath that figure sits a data point every corporate real estate director should watch more closely than vacancy itself: 75% of the quarter's gross demand didn't come from companies entering the market — it came from companies already established, renewing, expanding, subleasing or pre-leasing their current space.
If 75% of demand comes from companies already operating in the city reallocating their real estate budget toward higher-quality buildings, the relevant question for every owner stops being "how much demand is there?" and becomes "can my asset capture that reallocation?" A building that doesn't meet the certification, location and experience standards the average corporate mandate now requires is structurally excluded from that demand, regardless of how much the aggregate market grows.
At Klarock, we assess whether your office portfolio is positioned to capture consolidation demand — or whether it needs a repositioning plan before the price gap between Class A+ and the rest of the inventory widens further.
Reach out and a managing partner will contact you within 24 business hours.
Contact a Managing Partner